Opportunities for Business Owners

Owning and running a business comes with its share of challenges, but it also provides some unique tax planning flexibility. Business owners often have greater control over how they are compensated, when income and expenses are recognized, how they contribute toward retirement and, ultimately, how they transition out of the business. That flexibility creates some significant planning opportunities.

The key word here is planning. Most of these strategies need to be considered well before the end of the year if not years in advance. Below are several areas we think business owners should be reviewing with their Tanglewood Wealth Advisor and other tax professionals.

Choosing the Right Business Entity

How a business is structured impacts how its income is ultimately taxed. Sole proprietorships, partnerships, LLCs, S corporations and C Corporations can all have very different tax treatment.

For all but C Corps, the profits and losses flow direct to the owner’s (or “members” in the case of LLCs) tax return and taxed at personal tax rates. This is often called “pass-through” taxation. C Corps however, are considered a separate legal entity that pays its own tax on company profits. While salary and bonus compensation (W2) to C Corp owners is very similar to any other corporate firm, dividends paid to owners from the after-tax profits of the C Corp are subject to taxation again on the owner’s personal return. This double taxation is a significant consideration although other non-tax reasons might make the C Corp a good choice.

Many times, the structure that made sense when a business was started may not necessarily be the best structure after the business has grown and become more successful and profitable, particularly if the number of owners expand.

Taxes are certainly important, but they should not be the only consideration. Liability protection, control and ownership, employee benefits and the eventual transition or sale of the business should all be part of the planning analysis.

Maximize Retirement Plan Contributions

As we wrote in the first two articles of the series, retirement plans are one of the best tax planning tools and savings vehicles available to business owners.

Depending on the size of the company and number of employees, a business plan may consider a SEP IRA, SIMPLE IRA, 401(k), Safe Harbor 401(k), profit-sharing plan, a defined benefit pension plan or even an Employee Stock Ownership Plan (ESOP).

For a highly compensated business owner, we have found combining a 401(k) with a defined benefit pension plan can potentially allow for very large annual tax-deductible contributions – in some cases well into six figures.

Of course, there is no free lunch. Plans covering employees come with additional costs, funding requirements and administrative responsibilities. The objective is to find the right balance between maximizing the owner’s tax deductible retirement savings and providing an appropriate and worthwhile benefit to employees.

How is the Business Owner Paying Themselves?

Business owners have more flexibility than most employees when it comes to how and when they receive income.

Depending on the business structure, owner’s compensation might include salary, bonuses, corporation distributions, partnership income or dividends.

For an S Corporation owner with pass-through taxation, determining an appropriate balance between salary and distributions can be particularly important. Owners working in the business are generally required to pay themselves reasonable compensation, while additional profits may be distributed differently for tax purposes.

There may also be opportunities for the owner to defer income into the following tax year or accelerate business expenses into the current year.

Deferring income into next year is not always the right answer. If the business owner expects their tax rate to be higher next year, accelerating income may actually be beneficial. Likewise, an unusually profitable year may be a good opportunity to accelerate deductions.

We have found that end-of-year reviews should include both current and future year considerations and tax projections.

Evaluate the QBI Deduction

Many owners of pass-through businesses also qualify for the Qualified Business Income (QBI) deduction, which can allow eligible taxpayers to deduct a portion of their qualified business income.

Unfortunately, this is an area where the tax rules can get complicated quickly. The deduction can be limited based on taxable income, the type of business, W-2 wages paid by the company and other factors.

This is an area where tax projections can be especially useful. Income planning, retirement plan contributions and other deductions may reduce taxable income and potentially improve the QBI deduction at the same time.

Take Advantage of Depreciation

Business owners purchasing equipment and other qualifying property may be able to use Section 179 or bonus depreciation to deduct a significant portion of the cost in the year the property is placed in service.

This can provide a substantial deduction in a high-income year.

However, just because this deduction is available does not always mean that it provides the best overall tax result. If significantly higher income is expected in future years, preserving depreciation deductions may ultimately provide the greater tax benefit.

Buying a piece of equipment solely because it provides a tax deduction generally is not a very good investment strategy. The needs of the business should always come first while factoring in the after-tax cost of the equipment.

Put the Kids to Work

For family-owned businesses, employing children or other family members can create an interesting planning opportunity.

Reasonable compensation paid for legitimate work performed by a family member is generally deductible to the business and effectively shifts that income to the family member, who may be in a considerably lower tax bracket.

For children, there can be another benefit. Earned income creates eligibility to contribute to a Roth IRA. Funding a Roth IRA for a teenager or young adult can potentially give those dollars decades to compound tax-free.

Consider How Business Real Estate is Owned

Business owners who own the building or property used by their company should evaluate whether the real estate should be held separately from the operating business.

There can be several reasons for doing this, including liability protection and greater flexibility when the business is eventually sold or divided between heirs working in the business and those not.

An owner might sell the company but retain the real estate and lease it back to the new owner, creating an income stream in retirement. The property could also be sold separately or eventually transferred to family members.

How the real estate is owned should ideally be addressed well before a sale or transition is contemplated and made part of the long-term tax and estate plan.

Start Planning for the Exit Before the Exit

For many successful business owners, the business represents one of the largest if not the largest asset on their balance sheet. A sale may also represent one of the largest taxable events of their lifetime.

Unfortunately, the first time many owners begin thinking seriously about the tax consequences is after a potential buyer has already appeared. At that point, many planning opportunities may no longer be available.

Whether a transaction is structured as an asset sale or stock sale can have very different tax and liability consequences. Installment sales, gifting interests to family members and other strategies should be considered well in advance.

The earlier these conversations begin with knowledgeable planning professionals such as Tanglewood’s Wealth Advisors, as well as accountants and tax attorneys, the more options and strategies business owners are able to explore and build into their lifetime tax plan.

Charitable Giving Rules Are Changing in 2026

Tanglewood clients are an incredibly charitable group. I can honestly admit I have grown to be a more cheerful and generous giver after working with clients over the past two decades.

Our conversations with clients encompass not only the client’s overall purpose and goals for giving but the detailed strategies to accomplish them in a financially smart way within an ever-changing tax environment.

In July, we discussed some of various tax law changes that came about due to the One Big Beautiful Bill Act (OBBBA). This article focuses on those changes directly related to charitable giving. There are a number of new rules taking effect this year and next year that may be meaningful as we approach planning for the end of the year and into 2026.

A Deduction for Non-Itemizers

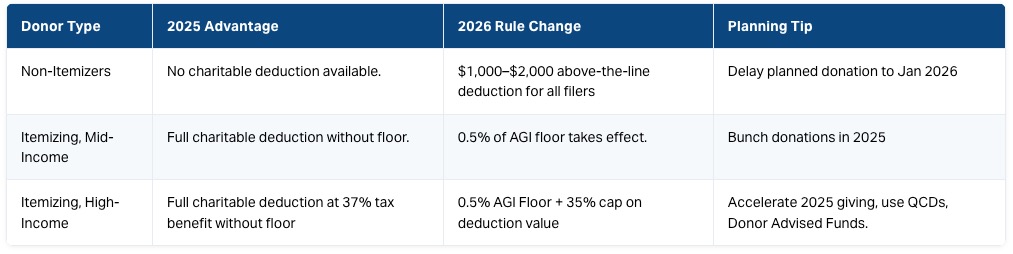
This provision was first introduced in 2020 and 2021 under the CARES Act, but starting in 2026, taxpayers who do not itemize will be able to claim a universal “above-the-line” charitable deduction.

  • $1,000 for single filers
  • $2,000 for married couples filing jointly

This deduction applies only to cash gifts made directly to qualified charities (not to donor-advised funds or private foundations). It creates a meaningful incentive for more households to give, even if they take the standard deduction.

Itemizers Face a 0.5% AGI Floor

Starting in 2026, itemized charitable deductions must exceed 0.5% of Adjusted Gross Income (AGI) before a deduction can be applied.

Example: A client with $300,000 of AGI, the first $1,500 of their charitable giving will not count toward their deduction.

This may make “bunching” donations — grouping multiple years’ gifts into one tax year — a more valuable strategy.

Cap on Tax Savings for High Earners

Starting in 2026, taxpayers in the top 37% bracket will see the value of their itemized deductions (including charitable contributions) capped at 35%, reducing the tax benefit on each deductible dollar.

QCDs Retain their Benefits

Qualified Charitable Distributions (QCDs) from IRAs remain untouched and become a more valuable strategy moving forward. Taxpayers age 70½ and older can still distribute up to $108,000 annually per person (2025) directly from an IRA to charity. These gifts avoid AGI limits and provide a very tax efficient way to give. Especially for those clients subject to Required Minimum Distributions. Since the QCD is excluded from AGI, it is beneficial all the way to the 37% tax bracket.

Planning Opportunities

  • 2025 Advantage: Current rules allow unrestricted deductions, with no AGI floor or cap on deduction value (with the exception of the % AGI limitations on gifts of appreciated assets.) That makes 2025 an attractive year for clients to “front-load” larger gifts or fund donor-advised accounts to maximize itemized deductions.
  • 2026 & Beyond: Non-itemizers will gain a new incentive, while higher-income donors face reduced tax benefits on gifts. Strategies like QCDs, donor advised funds, and bunching donations will play a bigger role.

The changes expand charitable giving tax breaks for many households while limiting benefits for others. If charitable giving is part of your annual tax planning, 2025 may be the right year to act on larger gifts before the new limits take effect.

As always, reach out to your Tanglewood Wealth Advisor to discuss how to approach charitable giving strategies specific to your situation.

7 Best Investments During a Recession

Keith Fenstad, Director of Wealth Planning, highlights recession-focused investment strategies and explains how defensive assets, income-generating investments, and portfolio diversification can help investors manage market uncertainty in U.S. News & World Report.

One Big Beautiful Bill

The One Big Beautiful Bill (OBBB) was signed into law by the president on July 4th after making its way through congress. There are many new provisions regarding income taxes and some important updates to the estate tax laws that will impact many Tanglewood clients. Below is a summary of that we think are some of the most impactful.

  • The current seven tax brackets (10%, 12%, 22%, 24%, 33%, 35%, 37%) that were introduced by the Tax Cuts and Jobs Act of 2017 and set to expire in 2026 are made permanent. There’s also a small extra inflation adjustment for only the lowest three brackets.

Now of course it goes without saying that NOTHING is “permanent” when it comes to tax law. In this context permanent means there is no sunset or future expiration until some future Congress votes to change it.

  • On the deduction front, the standard deduction is slightly enhanced. Starting this year, it will be $31,500 for joint filers, $23,625 for head of household, and $15,750 for all other filers, inflation adjusted thereafter. An increase of $1,500 / $1,125 / $750 respectively.

  • The Pease Limit which took a 3% “haircut” on total itemized deductions for high income earners cancelled by the TCJA is now permanently repealed.

  • The use of Miscellaneous itemized deductions (primarily unreimbursed employee expenses, tax prep fees, investment-related expenses) is permanently repealed.

  • Mortgage interest deduction cap remains at $750,000 of principal.

  • The OBBB raises the controversial State And Local Tax (SALT) deduction cap to $40,000 for tax years 2025 through 2029. The cap gets only a 1% annual inflation adjustment each year over that period. However, the SALT deduction gets reduced back toward $10,000 as Adjusted Gross Income (AGI) exceeds $500,000. It is fully phased out at $600,000 of AGI. For those in that $500k to $600k AGI range, this becomes a very important planning threshold. The additional $100k of income can effectively raise taxable income by $130K.

  • There is a new 0.5% floor on itemized charitable contributions. This is like the phaseout for deductible medical expenses where you have to be above the floor to start taking a deduction.

Regardless of whether a taxpayer is taking the standard deduction or itemizing, there are several new “above-the-line” deductions.

  • A new $1,000 per taxpayer above-the-line deduction for charitable contributions ($2,000 for joint filers). We had a similar provision for a $500 deduction in 2020 to spur giving during COVID era.

  • Starting in 2025 and continuing through 2028, seniors age 65 and older will be allowed to deduct $6,000 per person ($12,000 for married filing joint). This too starts to get phased out when income exceeds $75,000 single / $150,000 joint filers and becomes fully phased out at $175,000 individual and $250,000 joint. Essentially the backdoor way of alleviating the tax on Social Security income. Essentially the backdoor way of alleviating the tax on Social Security income.

  • A maximum deduction of $25,000 applicable to “Qualified Tips”.  The IRS plans to publish eligible occupations within 90 days. This tip income however is still subject to employment taxes. The deduction is phased out at $300,000 AGI for married filers and $150,000 for others It’s fully phased out at $550,000 for married, $400,000 for others.

  • A tax deduction against overtime pay is also included. “Qualified Overtime,” is defined straightforwardly as pay in excess of a worker’s regular rate. The deduction is to $25,000 for joint filers and $12,500 for all others. This too gets phased out at $300,000 AGI for MFJ, $150,000 for others, fully phased out at $550,000 for MFJ, $275,000 for others.

Both the deduction applicable to Tips and Overtime is effective for 2025 and expires at the end of 2028.

Other notable changes include.

  • The increase in the Alternative Minimum Tax exemption amounts were made permanent, however exemption phaseout thresholds were reset back to what they were in 2018 – $500,000 for singles and $1,000,000 for married filing joint. It also doubled the rate of phase out from 25% to 50% steepening the claw back for higher income earners.

  • The OBBB allows a deduction up to $10,000 of interest paid on new car loans for US-assembled vehicles purchases made in 2025 through 2028.

  • The bill expands qualified 529 expenses doubling the K-12 withdrawal limit from $10,000 to $20,000. It also adds new categories of qualified expenses including online resources, tutoring, high school dual-credit fees, educational therapies for students with disabilities, and exam costs, such as SAT fees. Also, workforce training, on-the-job training, apprenticeships supporting students pursuing vocational or alternative educational paths.

  • A new tax-preferred savings account dubbed “MAGA Program” allows for the creation of a new account for qualifying children born between January 1, 2025 and January 1, 2029.  Up to $5,000 per year is allowed by a parent or guardian for children until 8 years old. The government will add $1,000 to see the account. There are specific qualifications for investing in broad market US Index stock funds.

Finally on the estate planning side of things the big news here is the lifetime estate and gift tax exemptions which were facing a significant reduction at the end of 2025 was permanently increased to $15,000,000 per person indexed to inflation beginning in 2026. That’s a combined $30,000,000 for spouses putting the threat of estate tax exposure for many clients further out on the horizon.

These new rules present new and meaningful planning opportunities for nearly all clients. At Tanglewood we are prepared to help – using advanced modeling tools and an experienced team of Wealth Advisors. Together we can develop a personal, multi -year plan to not only look year by year, but over a lifetime.

Disclosures