Is There a New Normal for Inflation and Interest Rates?

We have experienced a dramatic seesaw in both inflation and interest rates since the onset of Covid.

Both inflation and interest rates plummeted in early 2020 in reaction to the steep drop in economic activity from the government enforced shutdowns and Covid-instilled fears.

In early 2021, inflation changed direction. It began to rise in reaction to shortages in goods that stay-at-home consumers demanded. The Federal Reserve (Fed) was slow to respond with higher rates in 2021, believing inflation was “transitory”…that it would end quickly when supply chains were repaired.

Yet when inflation continued its upward momentum into 2022, the Fed relented and began to raise rates in April of that year. Inflation peaked at over 9% in July of 2022, but the Fed, way behind the inflation curve, continued its steep rise in interest rates all the way to July of 2023. By then it was obvious that inflation was trending down.

This allowed the Fed to pause further rate increases and assess if they had already done enough. They have maintained their rate target of 5.25%-5.5% ever since. Until Chairman Powell’s press conference on December 13th, the Fed maintained a “hawkish” tone that it was ready to raise rates again.

At that meeting, Powell surprised the world by discussing rate cuts in 2024. It was an indication that holding rates above 5% for much longer may do more harm to the economy than good for inflation.

Throughout this entire seesaw of inflation and interest rates, the Fed predicted that the long-term neutral rate was 2.5%. In other words, once this bout of inflation is in the rear-view mirror, the Fed Funds rate would likely average around this level.

A base rate of 2.5% is 0.5% above their inflation target of 2%. This spread over inflation is close to its average spread since 1926 according to Stocks, Bonds, Bills, and Inflation Yearbook (2023). This would provide a return slightly greater than inflation yet not be so high as to discourage economic activity.

Of course, the rate would likely go much lower during periods of economic stress and much higher in periods where the economy is growing well above its non-inflationary potential.

With a stable base rate of 2.5% on short-term deposits, bond yields should also normalize. In other words, yields on Treasury bonds would increase as maturities lengthened. Again, turning to Ibbotson, a normal spread for the benchmark 10-year U.S. Treasury bond would produce an average yield of just above 4% if the base rate was 2.5%. (As noted in our December 2023 Commentary, the long-term average of that bond since 1790 is 4.35%!)

All of this hinges on the Fed hitting its inflation target of 2% (on average). How realistic is that? After all, the Fed could not get inflation up to its 2% target for over a decade before Covid (it hovered between 1% and 2%). Then, it went way above its target with the dislocations of Covid. Inflation peaked in mid-2022 and has trended down ever since.

While there are no guarantees, there is room for optimism that the 2% inflation target will be more easily met over the next decade than it was over the last.

In my Perspective, Inflation and Interest Rates (January 2021), I noted the three forces that restrained inflation over the prior decade were demographics, digitization, and globalization. These were powerful deflationary forces in that prior decade.
Source: The Wall Street Journal, BofA Research Investment Committee, Haver

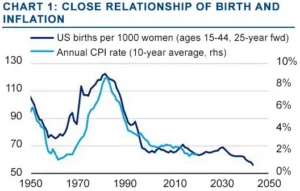
Both demographics and digitization (technology, including AI) remain potent deflationary forces. Chart 1 illustrates the close relationship over time between the US birth rate and the inflation rate (averaged over 10-year periods).

On the other hand, globalization has greatly diminished in favor of re-shoring and near-shoring. While this new direction is overdue to secure needed resources, the higher costs associated with these are inflationary.

Other longer-term inflationary forces have arisen in the last several years including higher real wages and the costs of mitigating climate change. (Keep in mind that most of the costs of building a renewable energy source to replace an existing fossil fuel energy source are inflationary. They do not add to ec1onomic output, they simply replace what already exists.)

In other words, there may be a balance between inflationary and deflationary forces that gives rise to a slightly higher but stable inflation rate (2%) in the future. This would allow for the interest rate picture that the Fed envisions.
Is There a New Normal for Inflation and Interest Rates?

We have experienced a dramatic seesaw in both inflation and interest rates since the onset of Covid.

Both inflation and interest rates plummeted in early 2020 in reaction to the steep drop in economic activity from the government enforced shutdowns and Covid-instilled fears.

In early 2021, inflation changed direction. It began to rise in reaction to shortages in goods that stay-at-home consumers demanded. The Federal Reserve (Fed) was slow to respond with higher rates in 2021, believing inflation was “transitory”…that it would end quickly when supply chains were repaired.

Yet when inflation continued its upward momentum into 2022, the Fed relented and began to raise rates in April of that year. Inflation peaked at over 9% in July of 2022, but the Fed, way behind the inflation curve, continued its steep rise in interest rates all the way to July of 2023. By then it was obvious that inflation was trending down.

This allowed the Fed to pause further rate increases and assess if they had already done enough. They have maintained their rate target of 5.25%-5.5% ever since. Until Chairman Powell’s press conference on December 13th, the Fed maintained a “hawkish” tone that it was ready to raise rates again.

At that meeting, Powell surprised the world by discussing rate cuts in 2024. It was an indication that holding rates above 5% for much longer may do more harm to the economy than good for inflation.

Throughout this entire seesaw of inflation and interest rates, the Fed predicted that the long-term neutral rate was 2.5%. In other words, once this bout of inflation is in the rear-view mirror, the Fed Funds rate would likely average around this level.

A base rate of 2.5% is 0.5% above their inflation target of 2%. This spread over inflation is close to its average spread since 1926 according to Stocks, Bonds, Bills, and Inflation Yearbook (2023). This would provide a return slightly greater than inflation yet not be so high as to discourage economic activity.

Of course, the rate would likely go much lower during periods of economic stress and much higher in periods where the economy is growing well above its non-inflationary potential.

With a stable base rate of 2.5% on short-term deposits, bond yields should also normalize. In other words, yields on Treasury bonds would increase as maturities lengthened. Again, turning to Ibbotson, a normal spread for the benchmark 10-year U.S. Treasury bond would produce an average yield of just above 4% if the base rate was 2.5%. (As noted in our December 2023 Commentary, the long-term average of that bond since 1790 is 4.35%!)

All of this hinges on the Fed hitting its inflation target of 2% (on average). How realistic is that? After all, the Fed could not get inflation up to its 2% target for over a decade before Covid (it hovered between 1% and 2%). Then, it went way above its target with the dislocations of Covid. Inflation peaked in mid-2022 and has trended down ever since.

While there are no guarantees, there is room for optimism that the 2% inflation target will be more easily met over the next decade than it was over the last.

In my Perspective, Inflation and Interest Rates (January 2021), I noted the three forces that restrained inflation over the prior decade were demographics, digitization, and globalization. These were powerful deflationary forces in that prior decade.

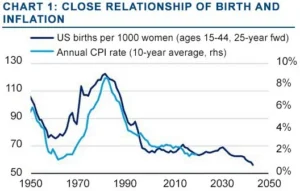
Both demographics and digitization (technology, including AI) remain potent deflationary forces. Chart 1 illustrates the close relationship over time between the US birth rate and the inflation rate (averaged over 10-year periods).

On the other hand, globalization has greatly diminished in favor of re-shoring and near-shoring. While this new direction is overdue to secure needed resources, the higher costs associated with these are inflationary.

Other longer-term inflationary forces have arisen in the last several years including higher real wages and the costs of mitigating climate change. (Keep in mind that most of the costs of building a renewable energy source to replace an existing fossil fuel energy source are inflationary. They do not add to ec1onomic output, they simply replace what already exists.)

In other words, there may be a balance between inflationary and deflationary forces that gives rise to a slightly higher but stable inflation rate (2%) in the future. This would allow for the interest rate picture that the Fed envisions.
Thoughtful Charitable Giving

On December 9th, the Financial Times (FT) published an opinion titled Does the American dream foster inequality?

I had great difficulty with the central theme of this article as noted in the following quote “…while Americans may recognize their nation’s problems with inequality, they have less desire to do something about it than their counterparts in the west.” The article focused entirely on government social programs.

After reading this article, I felt the need to write a Letter to the Editor which they published on December 15th, excerpted here.

“I think there is one important piece of the inequality puzzle that went unreported in this article. That is the role of our non-profit organizations in America. There is a huge network of non-profits (funded mostly by the wealthy) that add focused support in areas where it is most needed – education, food security, shelter, job assistance, and healthcare.”

For many of our clients, charitable giving is essential. Some are deeply involved in community non-profits — participating as volunteers, serving on boards, and/or giving generously. Others make charitable gifts a central element of their estate planning.

Tanglewood’s role is to help our clients understand the many charitable strategies and vehicles they can use to accomplish their goals. Very often the charitable gift can be leveraged through appropriate tax planning.

The most basic tax leverage is the gifting of highly appreciated securities to get both a tax deduction and the elimination of long-term capital gains. This can be done directly to a charity or to a client’s own Donor Advised Fund (DAF). We have set up well over 100 DAFs among our clients and ourselves. They are a great way of involving young family members in the family’s charitable planning.

Charitable giving can also be tied into other family goals. For example, the income from an asset can be split from the remainder value (value at the end of a period or at death).

A Charitable Remainder Trust retains the income for the client but gives the remainder to the charity of their choice. A Charitable Lead Trust gives the income away to charity but retains the remainder interest for family members at a significant discount.

Thoughtful charitable giving is in our firm’s DNA and is an important part of our wealth planning process.

The Rising Clout of the “Blue Collar” Workforce

Since at least the 1970s, most Americans were brought up believing “white collar” jobs were preferable to “blue collar” jobs. This became so ingrained that many parents who held good blue-collar jobs wanted “better” for their children.

This was institutionalized in the late 1970s when liberal educators remolded our entire K-12 education system around the college preparatory track. The stated purpose was to prepare every student for college enrollment. The entire curriculum was rebuilt with this objective.

It is as if those in charge felt we no longer needed to prepare our kids for careers as factory floor workers, hairdressers, welders, waiters, sales clerks, or all the other trades that make up well more than half of our workforce.

Because of the elevated status of college degrees, many jobs that could be accomplished with far less formal training started to require a degree. This in turn led to a dramatic increase in college enrollment, college costs, and student debt.

Source: United States Bureau of Labor Statistics, GIS Reports

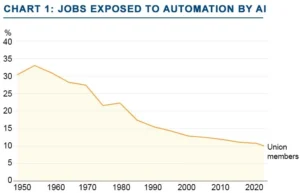
During this same period, there was a dramatic decline in union workers. See Chart 1. In the first half of the last century, it was the unionization of the blue-collar labor force – particularly in manufacturing – that provided wages and benefits that often exceeded those of many of the white-collar workers of that day.

The decline in private sector unions is closely tied to the decline in manufacturing employment. In the late 1940s, manufacturing accounted for 32% of all jobs compared to 8.5% today. Many of those remaining manufacturing jobs migrated to “right to work” states in the south. Employers in these states had much more flexibility in setting pay and benefits.

In the more recent decades, globalization and technology have also had a profound impact on the decline in U.S. manufacturing jobs. Private sector unions fought rearguard actions to preserve as many jobs as possible with pay packages that would not accelerate the union’s decline.

This multi-decade cycle of the ascendance of white-collar work over blue-collar work may be over. The pandemic shined a bright light on the so-called everyday people without whom life crawls to a standstill.

Private unions appear to be in the ascendancy as qualified blue-collar workers, after years of neglect, have become scarce! The recently passed legislation to boost infrastructure and manufacturing within the U.S. has run into this roadblock. For example, Taiwan Semiconductor had to push back plans for their new facilities outside of Phoenix citing a lack of skilled workers to build the facilities.

In addition, private unions have won major new concessions this year in a wide variety of companies and industries including UPS, longshoremen, and the airlines. The current UAW strike reflects new extremes in union demands.

Many companies such as Target, Amazon, and Kroger have seen the writing on the wall and have voluntarily raised wages dramatically. Virtually all frontline workers have received much more recognition and pay since the onset of the pandemic.

At the same time, white-collar workers may be going the opposite direction. The Challenger Report tracks all layoffs in the U.S. Recently it reported that we may be facing the first ever “white-collar recession”. They noted that most layoffs this past year have been among white-collar employees.

Source: The Wall Street Journal, Goldman Sachs Global Investment Research

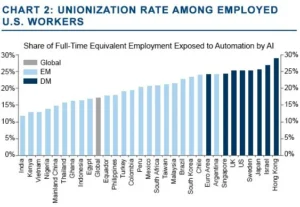
Research from Goldman Sachs suggests that 25% of American jobs could be automated by AI, compared to approximately 18% globally. See Chart 2. A very high percentage of these lost jobs will be from white-collar employment. Whereas there is no AI replacement for your electrician, plumber, mechanic, delivery person, etc, those that work with and distribute data are much easier to replace.

Gifts are an Effective Way to Curb Estate Tax Exposure

Clients often employ annual gifting as a way to transfer assets (plus the future appreciation of those assets) to children or other individuals to provide them immediate financial assistance or as part of an overall estate tax planning strategy.

First, let’s take a minute to review the annual gift exclusion, lifetime exemption and the current estate tax landscape.

The annual gift exclusion is the max amount any individual can gift to any recipient per year without having to take further action. The amount for 2023 is $17,000. There’s no limit to the number of annual exclusion gifts that can be made each year staying within $17,000 limit. The cumulative amount gifted in excess of $17,000 to any person reduces the giver’s lifetime exemption.

The lifetime exemption is the amount an individual can gift during their lifetime (in excess of the annual exclusion) or pass at death free of gift or estate taxes. In 2023, the lifetime exemption is set at $12,920,000 per person.

The annual gift exclusion has remained fairly constant for decades, only increasing with inflation each year in one-thousand dollar increments. The lifetime exemption on the other hand has changed many times and is currently at its all-time highest amount of $12,920,000. The 2018 Tax Cuts and Jobs Act (TCJA) was the last piece of legislation that ushered in this historically high exemption amount.

A lot of uncertainty remains. The provisions related to most of the changes brought on by the TCJA will expire at the end of 2025. In 2026, it’s expected the exemption will revert to about $7 million. The estate tax rate itself will remain at the current 40% level.

“Gift splitting” is a way for married couples to consider the gifts made by one spouse as being made by both spouses.

This either allows them to give more each year or reduces the impact to only one spouse’s lifetime exemption. Splitting can be for annual exclusion gifts or for larger gifts made against one’s lifetime exemption.

The gift can be made with community property or a donor’s separate property. Texas along with eight other states are community property jurisdictions. Community Property means that property acquired during marriage (except through gift and inheritance) is equally owned by both spouses.

When giving community property, the automatic presumption is that the gift is one-half from each spouse. Only if the amount gifted is in excess of the combined annual exclusion limit of $34,000 ($17,000 x 2) would a gift tax return (Form 709) need to be filed to account for the excess made by each.

When gifting Separate Property, a gift tax return must be filed to make the split election and both spouses will need to sign the return to consent to the gift.

It’s important to note that when splitting gifts, ALL gifts made during the year must be split. Spouses cannot selectively split some gifts made during the year and not others.

For those clients facing taxable estates, gifting can be an effective way of “freezing” or stemming the future growth of the estate. The objective being to shift that growth elsewhere – whether that be another person or to a trust.

Of course, before making any gifts (which are generally irrevocable), your Wealth Advisor can perform a complete review of your wealth plan and capital sufficiency projections. This ensures that the client’s own needs will be met first and then factor in potential gifts made now or in the future.

Opportunities and Considerations for Roth IRA Conversions

Roth IRA conversions have become an excellent tax planning strategy in the wealth plans of many of our client families.

What is a Roth IRA Conversion?

A Roth IRA conversion occurs when you move funds from a Traditional IRA or a SEP/SIMPLE IRA into a Roth IRA. Since an account holder is making a distribution of tax deferred dollars during a conversion, the funds converted are taxed as ordinary income in the year of conversion.

However, funds in a Roth IRA continue to grow tax-free throughout the account holder’s lifetime. (A 5-year holding rule applies to each conversion).

What are key opportunities for conversion?

The current marginal tax bracket is lower today than at actual distribution. This could be the case when clients are living on investment income from taxable accounts and expect significant Required Minimum Distributions (RMD) in the future from Traditional/SEP/SIMPLE IRAs.

For married couples, one spouse expects to outlive the other spouse. A surviving spouse transitions to a “Single” taxpayer which is subject to higher tax rates at lower income levels. The converted Roth funds can serve as tax-free income to supplement taxable sources of income and maintain the survivor’s current standard of living.

Huge charitable deductions or carryforwards. A Roth conversion fills up the income that helps absorb a greater percentage of the charitable deduction. (Charitable deductions are subject to Adjusted Gross Income limitations).

Net Operating Loss (NOL) Carryforwards. Ordinary income taxes from a Roth conversion can offset NOL losses in years where businesses may be experiencing setbacks or did not generate any profits.

Roth IRA funds are an excellent vehicle to maximize funds for transferring wealth to the next generation. When non-spouse beneficiaries inherit Roth IRA accounts, the account can continue to grow tax free until the last day of the 10th year following the year of the decedent’s death. (Some exceptions apply.)

High income earners at top brackets can convert now before rates sunset at the end of 2025. Depending on a client’s overall financial situation, it may make sense for high-income earners to consider conversions at 37% today which is still more favorable than the anticipated top tax rate reversion back to 39.6% in 2026. (This provision within the Tax Cuts and Jobs Act of 2017 expires at the end of 2025.)

What are some important considerations when implementing a Roth conversion?

Cash is available for tax payment. Cash is available outside of qualified accounts and not needed for living expenses.

Higher taxable income can result in increased Medicare insurance premiums. For those who are paying Medicare premiums for Part B and D, a Roth conversion will increase taxable income which could affect the Income-Related Monthly Adjustment Amount (IRMAA) that future premiums are based on. Note – the benefits of tax-free compounding on a Roth IRA for an owner’s lifetime can outweigh the additional premium dollars that are spent.

Consider Net Investment Income Tax. Clients need to be aware that a conversion that increases their Modified Adjusted Gross Income (MAGI) levels over $200K (Single) or $250K (Married filing joint) will be subject to the 3.8% “net investment income tax” (Medicare surtax).

Our tax planning tools can help estimate the optimal amount for conversion based on each client’s unique situation. Please contact your Wealth Advisor to help evaluate a Roth conversion strategy that may enhance your wealth plan.

Education Funding with 529 Plans

In my experience providing financial counseling, I have fielded many questions with regards to the best ways to fund college education for a child or grandchild.

When it comes to selecting a vehicle for your education saving, there are a variety of options. However, often the best solution is a 529 plan. A 529 plan offers the benefit of tax-free growth and withdrawals for qualified education expenses.

A pre-paid in-state tuition plan is a specific type of 529 program. These plans have the most limited options for use and can have drawbacks if your student ends up not attending school or goes to an out-of-state school.

The 529 savings plan is the more flexible of the two accounts and can be used for a wider variety of costs, including associated expenses like room and board, and vocational apprenticeship programs. K-12 tuition expenses and student loan payments are also allowed up to $10,000.

Contribution limits are quite generous. In addition to an annual exclusion of $17,000 per person for 2023, one could also “superfund” a 529 plan by using up to 5 years’ worth of annual gift exclusions in one year. This could add up to $170,000 combined between spouses.

There are a variety of 529 plan providers available which offer a range of investments options, a common choice being a target enrollment fund which begins with more growth oriented strategies and becomes more conservative over time as your student approaches starting school. This provides the real advantage of potential long-term appreciation of your savings above and beyond the rising costs of education.

If your student does not use all of the 529 funds for whatever reason, the beneficiary could be changed to another family member including even yourself.

As a last resort, non-qualified distributions can be made for needs other than education, like helping your student with a home down payment. These distributions would be subject to taxation on the growth in the account plus a 10% penalty. A distribution as a result of receiving a scholarship would be an exception to this.

At Tanglewood, we are pleased to answer any questions you may have about how best to fund education for your student. Please reach out to your Wealth Advisor to begin the conversation.

Helping Adult Children Buy A Home

High home prices, high interest rates, low inventory, and tough competition have made many prospective buyers feel that home ownership is out of reach entirely or they can no longer afford the home they want.

This environment has prompted new ways of approaching a potential purchase and led to more conversations with clients about helping a child buy a home. There are several potential ways parents can help but only after addressing the first and most important question:”Do we have enough to help at all?” (As Keith discussed on the previous page, our Capital Sufficiency pillar is an excellent tool that can be used to find the answer.) Once that critical question is addressed, consider the following:

Outright Gift

If you are comfortable gifting money, you could give enough cash to your adult child to buy the home outright, assist with the down payment, or help with making mortgage payments. Depending on how large the gift is and how it is structured, you may need to file a gift tax return. You may also be asked to confirm that it is a gift and not a loan so as not to interfere with mortgage underwriting.

Intrafamily Loan / Landlord

In lieu of an outright gift, you could become the “family bank” and loan the money to your adult child. This works best when financing the entire purchase. As an alternative, you could buy the house and then rent it to your adult child. In both cases it is important that you properly document any loan or rental agreement and associated tax reporting on income.

Be On The Hook

If your adult child is struggling to meet mortgage loan underwriting requirements (e.g., they are self-employed), you could co-sign the mortgage or co-borrow. The co-signer is on the mortgage to guarantee the loan for the borrower. The co-borrower has equal responsibility to pay the mortgage.

Gift or Sell the Family Home

If you find yourself in a position of wanting to downsize and your adult child wants the family home, you could sell it or gift it to them. In both cases, it is wise to hire a real estate appraiser to determine and document the fair market value of the home, as well as hire an attorney to prepare and file any required paperwork to properly document the transfer of ownership.

Each of these has its unique advantages and disadvantages along with the potential impact on your taxes (income, gift, and estate), family dynamics, liability, financial independence, and estate planning.

Helping an adult child is an admirable goal and a big financial decision to make. We encourage you to contact your Wealth Advisor if it is something you are considering.

The Major Forces Molding Our Future

Daily changes within our economy are imperceptibly small except in highly unusual circumstances like the impact of Covid. Yet our economy is always in a state of change, driven by powerful long-term economic forces.

Today, the dominant factors steering our economy are demographics, social strains, government policies/debt, geopolitical realignment, technology, and climate change. These forces will shape our future.

Source: Yardeni Research, Inc.
Source: The WSJ, OECD & Moody’s Investor Service, Chart: Axios Visuals

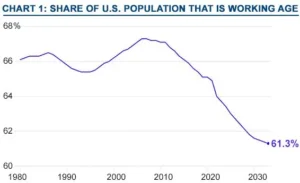
Demographics. The world population is getting older as people live longer and have fewer children. The decline in the (traditional) working age population will continue. See Chart 1. Without a pickup in productivity, economic growth will slow, and standards of living will stagnate.

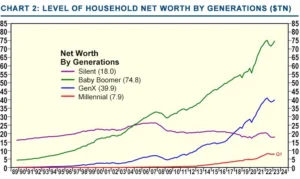
Social Strains. For much of the past three decades a disproportionate amount of income and wealth creation went to a smaller percentage of people, particularly those with capital in either the private or public markets. Most of today’s wealth resides within the Boomer generation (and this is concentrated in the wealthiest 10%). See Chart 2. Also, low income wages stagnated as many jobs moved offshore while minimum wages barely budged. This has strained social cohesion.


Government Policies/Debt. Government spending has skyrocketed. Given the flood of new money coming from the Infrastructure, Chips, and Clean Energy bills (on top of Entitlements and Defense increases), it is not likely to fall off. And of course, so much of it is borrowed (deficit spending) that the interest bill to the Federal government is soaring.

Geopolitical Realignment. Francis Fukuyama’s The End of History in 1989 suggested that after the fall of communism, Western liberal democracy had “won” and may be regarded as the final evolution of human government. For a time, this notion gained wide acceptance. Yet history did not end and there has been a rapidly growing divergence between liberal democracies and autocratic governments, particularly since Xi Jinping became president of China.

Technology. Advancements in technology over the past several decades have irrevocably changed the way we live and work. From the personal computer to the internet, email, smart phones, Zoom, and on and on. Now we are told that AI (artificial intelligence) will change our world even more dramatically than its precursors and at a faster pace.

Climate Change. Climate change is real although the causes extend far beyond fossil fuels. For example, just the increase in carbon dioxide from California’s 2020 wildfires was estimated in Environmental Pollution (10/22) to be twice the total of all California’s reductions over 15 years.

How might these disparate trends interact to mold our future?

Efficiency to Resilience. This is the force behind reshoring and increased defense budgets. Interest rates will be higher, inflation will likely be higher too as we turn from free markets and free trade toward industrial policies and managed trade. In addition, the impact of weather events – flooding, wind damage, extreme heat, droughts – will take ever greater resources just to fortify what is in place. This implies higher inflation and higher interest rates than we recently enjoyed.

Reductions in Inequality. Entitlement reform is essential if we are to pay for the increased demands on government. (Reduction in benefits to the wealthy and higher paid will be necessary.)

Wages will likely continue to rise across the bottom half of the income spectrum as a shrinking workforce increases labor’s bargaining power. Income taxes are likely to be even more progressive along with higher estate transfer costs.

New Global Powers. China may “hollow out” as it suffers from a rapidly aging workforce (a result of the one-child policy) along with the rise in capital flight and out migration by some of the wealthiest and brightest. The Middle East and Africa are likely to gain increasing power due to younger demographics and commodity wealth. India should benefit from its young, tech savvy workforce.

AI, the Wild Card. While many worry about a tragic Terminator type of outcome, there is real promise in areas like education, health care, and routine back-office services. If we are to have the long-awaited productivity boom, this will be the source.

The Next Generation of Comprehensive Planning Illustrations

Nearly 20 years ago I developed the first iteration of Tanglewood’s proprietary Retirement Illustration. This started the expansion of our comprehensive wealth planning initiative for Wealth Management clients.

The goal was to use the Illustration as a proprietary tool to quantify and visualize the alignment between a client’s invested assets and various future income streams (such as social security, pensions, etc.), with their projected future spending needs throughout their retirement years. It has served us very well.

Over the years the Illustration saw many enhancements from initial plan creation and updates to incorporating current tax laws, future tax law changes, Roth conversions, gifting and more.

I give credit to Victor Powell for advancing the spreadsheet’s capabilities and user friendliness. He took it to the next level after he joined the team in 2014.

Along with the advancements in the tool itself was the evolution of its delivery. It started with me bringing in a stack of printouts into a meeting considering various scenarios and assumptions. I now cringe at the thought of covering half the conference room table with a sea of paper reports. A major advancement was the development of an online presentation that provided the ability to make changes on the fly and immediately see the impact of those changes. Tanglewood uses tools like this to help enhance client awareness of lifetime resources and needs.

Having that level of interaction and immediate “what if” variability offered much more client confidence and ownership in the results. We want every wealth management client to see the final results as THEIR plan.

As good as it was in helping answer important questions regarding retirement timing, income and asset distribution planning, industry tools and technology were swiftly advancing as well. Over the past several years, we thoroughly evaluated several comprehensive planning programs and selected one that best supports the four pillars of Tanglewood’s wealth planning process.

Our new comprehensive program checked all the right boxes for us as it provides an exceptional balance between depth and detail without sacrificing ease of use and simplicity. Here are some of the highlights of what this advanced tool offers as part of our hands on wealth planning.

Goal Based Financial Planning:

A comprehensive goals-based approach with the capability to create comprehensive plans that incorporate retirement planning, investments, insurance, tax planning, college funding and more.

Scenario Modeling:

We can run multiple scenarios to analyze the impact of different variables in real-time. We can make adjustments to lifestyle spending, savings rates, retirement ages, investments and other factors to understand the potential change in outcomes.

We can also incorporate probability analysis that goes beyond traditional linear projections to understand the impact of variable returns over time.

Interactive Client Portal:

The software allows us to provide a secure and user-friendly client portal, enabling interactive access to a client’s financial plan as well as progress toward their goals. It is also capable of account aggregation to bring together all investment accounts, assets, and debts to build a balance sheet that automatically updates values over time.

Tax Planning and Optimization:

We find the tax planning features, including future tax projections, tax-efficient withdrawal strategies and Roth conversion analysis particularly helpful. Helping clients make wise decisions regarding their lifetime tax exposure not just year-over-year.

Cash Flow Management:

With its robust cash flow management capabilities we can track client’s income, expenses and debt repayments. It automatically categorizes these transactions from linked accounts, generates reports and offers insights into spending patterns for making better budgeting decisions. Detailed cash flow transactions are for the client’s eyes only and not seen by your Wealth Advisor unless shared by the client.

With this program we can provide greatly enhanced flexibility and “what if” capabilities and with it we can provide clients the confidence, clarity and definitive path to move forward in reaching their personal financial goals. Equally important is that as each client’s situation and goals change, the plan can easily change direction as well.

We are working with additional clients on this platform seemingly every day in preparation for Wealth Planning review meetings. Contact your Wealth Advisor to discuss this further or to set up a review meeting at your convenience.