The Right Things

Winston Churchill once stated, “Americans will always do the right thing after they have tried everything else.”

Of course, “the right thing” is in the eye of the beholder. Yet there is broad agreement on some very basic long-term guiding principles for our country, including:

  • Respect and support for the institutions that made this country the envy of the world: rule of law, equality of opportunity, first class public education, independent judiciary, free markets, and true democratic participation.

  • Building and maintaining a Department of Defense capable of defending our country against all adversaries.

  • Public debt that can easily be supported through all economic cycles without stressing other governmental responsibilities. We cannot continue to post enormous fiscal deficits.

  • Providing necessary help for those Americans, who through no fault of their own, cannot fully support themselves.

  • Build and maintain the infrastructure necessary to run a first class 21st century country.

  • Provide the regulatory backdrop necessary to support Americans’ general health and safety but not so much as to interfere with the growth and competitiveness of our economy.

Whereas there is general agreement on these principles, the devil is in the details of how to implement them. The Founding Fathers recognized that there would be disagreements, so they built into each of the three branches of government safeguards from tyrannical rule by a majority.

Perhaps what we most lack is reasonable debate on the matters of implementation and cooperative compromise. No side has all the right answers. This has never been easy but is even harder in this era of passions inflamed by social media and polarized television formats.

Many of you know that one of my passions is education, particularly today’s poor performing public education system. Certainly, there are many top performing school districts, but national scores are beyond dismal.

Our kids are our future. Poor performing public schools need accountability which necessitates more community and parental involvement and/or competitive alternatives such as charter schools.

I have also written many times in the past about the unsustainable path of our national debt obligations. For example, I wrote a Perspective piece titled, Debt, Taxes, Inflation, and Repudiation in January 2010 from which I take the following quote: Our government continues to increase its long-term spending commitments (relative to revenues) which were already on a collision course with its ability to pay.

Nothing has changed since then except we have gone from 60% to 100% debt to GDP and soaring interest costs. (On June 18th the CBO increased this year’s estimated deficit to $1.9 trillion – just shy of the all-time high posted in the worst of Covid – and this is with a strong economy!)

Real compromise starts at the intersection of fairness in taxes and fairness in benefits. While I am a fiscal conservative, I recognize the need to raise taxes as an essential element for reaching the goals stated at the beginning of this piece.

It is also apparent to me that the lion’s share of any tax increases must come from the wealthiest Americans. The drivers of our current economy reward this group far more than past generations and are causing social strains across our nation.

We came together after WWII to pay down the enormous government debt built up during that war. Income tax rates reached 90%! Can we come together and pay for the government we need to avoid WWIII?

Finally, a major compromise is now necessary for entitlements. This is the elephant in the room that almost all politicians have negligently avoided. As virtually everyone acknowledges in private, unanticipated increased longevity has made our current promises unsustainable.

Many very intelligent proposals have been made for entitlement reform. The easiest to implement would be means testing annually (progressive ineligibility for higher earning above some number); increasing the eligibility age for those now under say 50; CPI inflation adjustment instead of the current wage inflation number.

America today is based on past decisions; America tomorrow is based on today’s. Who is in charge? WE ARE! Let’s demand more from those in a position to make needed changes. It is about time we proved Winston Churchill right.
ETF Revolution in Investment Management

Exchange Traded Fund (ETF).

In 1993, State Street Global Advisors introduced a new structure for housing an investment portfolio, the Exchange Traded Fund (ETF). The first ETF was the SPDR S&P 500 Trust (SPY).

What is an Exchange Traded Fund? ETFs are a type of pooled investment security that can be bought and sold much like an individual stock. The main difference between an ETF and a mutual fund is that though a mutual fund is also a pooled investment, it trades only once a day after the market closes.

Benefits of ETFs.

ETFs offer several advantages over mutual funds, including:

  • More Transparency.

  • Lower cost.

  • Tax efficiency.

  • Certainty.

Transparency. Traditional mutual funds only report their underlying security positions on a quarterly basis. ETF holders, on the other hand, can view the fund’s holdings more frequently.

Low cost. Although the costs of purchasing and owning mutual funds have come down tremendously over the past several decades, they still cannot compete with the low cost of most ETFs. Many of the larger ETFs have ongoing operating costs of below 0.1% per year.

In addition, as ETFs trade like stocks, they are mostly bought and sold with no costs. (Most mutual funds can also be bought with no front-end costs by the fund, but the custodian may charge a fee for making the transaction. Schwab charges $12 to Tanglewood clients for many mutual fund transactions.)

Tax efficiency. ETFs are extremely tax efficient. Partly this is due to the passive nature of their approach – like index mutual funds. In addition, ETFs have a cooperative structure with the offering institution that “exchanges” some security trades before a taxable sale.

Certainty. ETFs were originally designed to be passive index vehicles. Whatever index the ETF was following was exactly the securities it intended to hold. The underlying investments only changed as the index changed.

These advantages are attractive to both institutional and individual investors. ETFs meet the need for broad market exposure with a single trade.

Evolution of ETFs.

During the 1990s and early 2000s, ETFs remained primarily broad asset class vehicles.

Source: Statista 2024

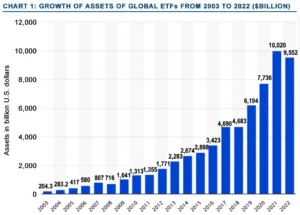
However, as their tax efficiency, low costs, ease of use and advancement in trading technology was validated, ETF usage expanded rapidly, from $204 billion in 2003 to over $10 trillion in 2021. See Chart 1. (The decline in 2022 was due to the bear market in stocks and bonds.)

This rapid increase in popularity was led by the introduction of more focused areas of investment, including single sectors (technology, energy, etc.), value or growth only, single countries and much more. These offerings have been dubbed factor funds.

This evolution has given investors, including Tanglewood, the ability to further define the criteria for both our equity and bond holdings. For example, one of our factor ETF holdings invests only in a “quality” subset of the S&P 500 index – those stocks that meet stringent earnings and balance sheet tests.

Until recently, the holdings within factor ETFs were held passively according to the criteria of the “factor”. Rebalancing is typically done on a set schedule, often annually.

The very latest innovation is actively managed ETFs. This removes the final major distinction between most mutual funds and ETFs. This brings truly active management into the low cost, tax efficient, transparent world of ETFs.

Two of the great managers that we have used in a mutual fund format have opened active ETF funds which we have invested in.

I have had a long enough career to have experienced each change along the way. It is incredibly satisfying to have the range of options and efficiencies of today’s marketplace.

Is There a New Normal for Inflation and Interest Rates?

We have experienced a dramatic seesaw in both inflation and interest rates since the onset of Covid.

Both inflation and interest rates plummeted in early 2020 in reaction to the steep drop in economic activity from the government enforced shutdowns and Covid-instilled fears.

In early 2021, inflation changed direction. It began to rise in reaction to shortages in goods that stay-at-home consumers demanded. The Federal Reserve (Fed) was slow to respond with higher rates in 2021, believing inflation was “transitory”…that it would end quickly when supply chains were repaired.

Yet when inflation continued its upward momentum into 2022, the Fed relented and began to raise rates in April of that year. Inflation peaked at over 9% in July of 2022, but the Fed, way behind the inflation curve, continued its steep rise in interest rates all the way to July of 2023. By then it was obvious that inflation was trending down.

This allowed the Fed to pause further rate increases and assess if they had already done enough. They have maintained their rate target of 5.25%-5.5% ever since. Until Chairman Powell’s press conference on December 13th, the Fed maintained a “hawkish” tone that it was ready to raise rates again.

At that meeting, Powell surprised the world by discussing rate cuts in 2024. It was an indication that holding rates above 5% for much longer may do more harm to the economy than good for inflation.

Throughout this entire seesaw of inflation and interest rates, the Fed predicted that the long-term neutral rate was 2.5%. In other words, once this bout of inflation is in the rear-view mirror, the Fed Funds rate would likely average around this level.

A base rate of 2.5% is 0.5% above their inflation target of 2%. This spread over inflation is close to its average spread since 1926 according to Stocks, Bonds, Bills, and Inflation Yearbook (2023). This would provide a return slightly greater than inflation yet not be so high as to discourage economic activity.

Of course, the rate would likely go much lower during periods of economic stress and much higher in periods where the economy is growing well above its non-inflationary potential.

With a stable base rate of 2.5% on short-term deposits, bond yields should also normalize. In other words, yields on Treasury bonds would increase as maturities lengthened. Again, turning to Ibbotson, a normal spread for the benchmark 10-year U.S. Treasury bond would produce an average yield of just above 4% if the base rate was 2.5%. (As noted in our December 2023 Commentary, the long-term average of that bond since 1790 is 4.35%!)

All of this hinges on the Fed hitting its inflation target of 2% (on average). How realistic is that? After all, the Fed could not get inflation up to its 2% target for over a decade before Covid (it hovered between 1% and 2%). Then, it went way above its target with the dislocations of Covid. Inflation peaked in mid-2022 and has trended down ever since.

While there are no guarantees, there is room for optimism that the 2% inflation target will be more easily met over the next decade than it was over the last.

In my Perspective, Inflation and Interest Rates (January 2021), I noted the three forces that restrained inflation over the prior decade were demographics, digitization, and globalization. These were powerful deflationary forces in that prior decade.

Source: The Wall Street Journal, BofA Research Investment Committee, Haver

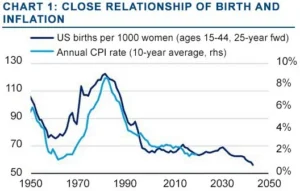
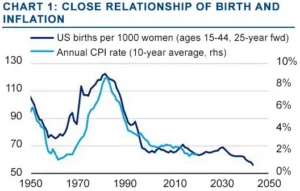
Both demographics and digitization (technology, including AI) remain potent deflationary forces. Chart 1 illustrates the close relationship over time between the US birth rate and the inflation rate (averaged over 10-year periods).

On the other hand, globalization has greatly diminished in favor of re-shoring and near-shoring. While this new direction is overdue to secure needed resources, the higher costs associated with these are inflationary.

Other longer-term inflationary forces have arisen in the last several years including higher real wages and the costs of mitigating climate change. (Keep in mind that most of the costs of building a renewable energy source to replace an existing fossil fuel energy source are inflationary. They do not add to ec1onomic output, they simply replace what already exists.)

In other words, there may be a balance between inflationary and deflationary forces that gives rise to a slightly higher but stable inflation rate (2%) in the future. This would allow for the interest rate picture that the Fed envisions.

Is There a New Normal for Inflation and Interest Rates?

We have experienced a dramatic seesaw in both inflation and interest rates since the onset of Covid.

Both inflation and interest rates plummeted in early 2020 in reaction to the steep drop in economic activity from the government enforced shutdowns and Covid-instilled fears.

In early 2021, inflation changed direction. It began to rise in reaction to shortages in goods that stay-at-home consumers demanded. The Federal Reserve (Fed) was slow to respond with higher rates in 2021, believing inflation was “transitory”…that it would end quickly when supply chains were repaired.

Yet when inflation continued its upward momentum into 2022, the Fed relented and began to raise rates in April of that year. Inflation peaked at over 9% in July of 2022, but the Fed, way behind the inflation curve, continued its steep rise in interest rates all the way to July of 2023. By then it was obvious that inflation was trending down.

This allowed the Fed to pause further rate increases and assess if they had already done enough. They have maintained their rate target of 5.25%-5.5% ever since. Until Chairman Powell’s press conference on December 13th, the Fed maintained a “hawkish” tone that it was ready to raise rates again.

At that meeting, Powell surprised the world by discussing rate cuts in 2024. It was an indication that holding rates above 5% for much longer may do more harm to the economy than good for inflation.

Throughout this entire seesaw of inflation and interest rates, the Fed predicted that the long-term neutral rate was 2.5%. In other words, once this bout of inflation is in the rear-view mirror, the Fed Funds rate would likely average around this level.

A base rate of 2.5% is 0.5% above their inflation target of 2%. This spread over inflation is close to its average spread since 1926 according to Stocks, Bonds, Bills, and Inflation Yearbook (2023). This would provide a return slightly greater than inflation yet not be so high as to discourage economic activity.

Of course, the rate would likely go much lower during periods of economic stress and much higher in periods where the economy is growing well above its non-inflationary potential.

With a stable base rate of 2.5% on short-term deposits, bond yields should also normalize. In other words, yields on Treasury bonds would increase as maturities lengthened. Again, turning to Ibbotson, a normal spread for the benchmark 10-year U.S. Treasury bond would produce an average yield of just above 4% if the base rate was 2.5%. (As noted in our December 2023 Commentary, the long-term average of that bond since 1790 is 4.35%!)

All of this hinges on the Fed hitting its inflation target of 2% (on average). How realistic is that? After all, the Fed could not get inflation up to its 2% target for over a decade before Covid (it hovered between 1% and 2%). Then, it went way above its target with the dislocations of Covid. Inflation peaked in mid-2022 and has trended down ever since.

While there are no guarantees, there is room for optimism that the 2% inflation target will be more easily met over the next decade than it was over the last.

In my Perspective, Inflation and Interest Rates (January 2021), I noted the three forces that restrained inflation over the prior decade were demographics, digitization, and globalization. These were powerful deflationary forces in that prior decade.

Both demographics and digitization (technology, including AI) remain potent deflationary forces. Chart 1 illustrates the close relationship over time between the US birth rate and the inflation rate (averaged over 10-year periods).

On the other hand, globalization has greatly diminished in favor of re-shoring and near-shoring. While this new direction is overdue to secure needed resources, the higher costs associated with these are inflationary.

Other longer-term inflationary forces have arisen in the last several years including higher real wages and the costs of mitigating climate change. (Keep in mind that most of the costs of building a renewable energy source to replace an existing fossil fuel energy source are inflationary. They do not add to ec1onomic output, they simply replace what already exists.)

In other words, there may be a balance between inflationary and deflationary forces that gives rise to a slightly higher but stable inflation rate (2%) in the future. This would allow for the interest rate picture that the Fed envisions.

Thoughtful Charitable Giving

On December 9th, the Financial Times (FT) published an opinion titled Does the American dream foster inequality?

I had great difficulty with the central theme of this article as noted in the following quote “…while Americans may recognize their nation’s problems with inequality, they have less desire to do something about it than their counterparts in the west.” The article focused entirely on government social programs.

After reading this article, I felt the need to write a Letter to the Editor which they published on December 15th, excerpted here.

“I think there is one important piece of the inequality puzzle that went unreported in this article. That is the role of our non-profit organizations in America. There is a huge network of non-profits (funded mostly by the wealthy) that add focused support in areas where it is most needed – education, food security, shelter, job assistance, and healthcare.”

For many of our clients, charitable giving is essential. Some are deeply involved in community non-profits — participating as volunteers, serving on boards, and/or giving generously. Others make charitable gifts a central element of their estate planning.

Tanglewood’s role is to help our clients understand the many charitable strategies and vehicles they can use to accomplish their goals. Very often the charitable gift can be leveraged through appropriate tax planning.

The most basic tax leverage is the gifting of highly appreciated securities to get both a tax deduction and the elimination of long-term capital gains. This can be done directly to a charity or to a client’s own Donor Advised Fund (DAF). We have set up well over 100 DAFs among our clients and ourselves. They are a great way of involving young family members in the family’s charitable planning.

Charitable giving can also be tied into other family goals. For example, the income from an asset can be split from the remainder value (value at the end of a period or at death).

A Charitable Remainder Trust retains the income for the client but gives the remainder to the charity of their choice. A Charitable Lead Trust gives the income away to charity but retains the remainder interest for family members at a significant discount.

Thoughtful charitable giving is in our firm’s DNA and is an important part of our wealth planning process.

The Rising Clout of the “Blue Collar” Workforce

Since at least the 1970s, most Americans were brought up believing “white collar” jobs were preferable to “blue collar” jobs. This became so ingrained that many parents who held good blue-collar jobs wanted “better” for their children.

This was institutionalized in the late 1970s when liberal educators remolded our entire K-12 education system around the college preparatory track. The stated purpose was to prepare every student for college enrollment. The entire curriculum was rebuilt with this objective.

It is as if those in charge felt we no longer needed to prepare our kids for careers as factory floor workers, hairdressers, welders, waiters, sales clerks, or all the other trades that make up well more than half of our workforce.

Because of the elevated status of college degrees, many jobs that could be accomplished with far less formal training started to require a degree. This in turn led to a dramatic increase in college enrollment, college costs, and student debt.

Source: United States Bureau of Labor Statistics, GIS Reports

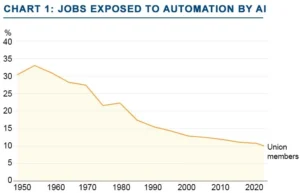
During this same period, there was a dramatic decline in union workers. See Chart 1. In the first half of the last century, it was the unionization of the blue-collar labor force – particularly in manufacturing – that provided wages and benefits that often exceeded those of many of the white-collar workers of that day.

The decline in private sector unions is closely tied to the decline in manufacturing employment. In the late 1940s, manufacturing accounted for 32% of all jobs compared to 8.5% today. Many of those remaining manufacturing jobs migrated to “right to work” states in the south. Employers in these states had much more flexibility in setting pay and benefits.

In the more recent decades, globalization and technology have also had a profound impact on the decline in U.S. manufacturing jobs. Private sector unions fought rearguard actions to preserve as many jobs as possible with pay packages that would not accelerate the union’s decline.

This multi-decade cycle of the ascendance of white-collar work over blue-collar work may be over. The pandemic shined a bright light on the so-called everyday people without whom life crawls to a standstill.

Private unions appear to be in the ascendancy as qualified blue-collar workers, after years of neglect, have become scarce! The recently passed legislation to boost infrastructure and manufacturing within the U.S. has run into this roadblock. For example, Taiwan Semiconductor had to push back plans for their new facilities outside of Phoenix citing a lack of skilled workers to build the facilities.

In addition, private unions have won major new concessions this year in a wide variety of companies and industries including UPS, longshoremen, and the airlines. The current UAW strike reflects new extremes in union demands.

Many companies such as Target, Amazon, and Kroger have seen the writing on the wall and have voluntarily raised wages dramatically. Virtually all frontline workers have received much more recognition and pay since the onset of the pandemic.

At the same time, white-collar workers may be going the opposite direction. The Challenger Report tracks all layoffs in the U.S. Recently it reported that we may be facing the first ever “white-collar recession”. They noted that most layoffs this past year have been among white-collar employees.

Source: The Wall Street Journal, Goldman Sachs Global Investment Research

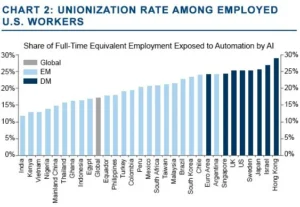
Research from Goldman Sachs suggests that 25% of American jobs could be automated by AI, compared to approximately 18% globally. See Chart 2. A very high percentage of these lost jobs will be from white-collar employment. Whereas there is no AI replacement for your electrician, plumber, mechanic, delivery person, etc, those that work with and distribute data are much easier to replace.

The Major Forces Molding Our Future

Daily changes within our economy are imperceptibly small except in highly unusual circumstances like the impact of Covid. Yet our economy is always in a state of change, driven by powerful long-term economic forces.

Today, the dominant factors steering our economy are demographics, social strains, government policies/debt, geopolitical realignment, technology, and climate change. These forces will shape our future.

Source: Yardeni Research, Inc.
Source: The WSJ, OECD & Moody’s Investor Service, Chart: Axios Visuals

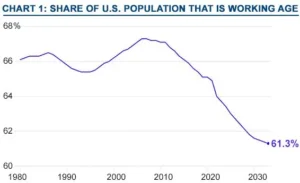
Demographics. The world population is getting older as people live longer and have fewer children. The decline in the (traditional) working age population will continue. See Chart 1. Without a pickup in productivity, economic growth will slow, and standards of living will stagnate.

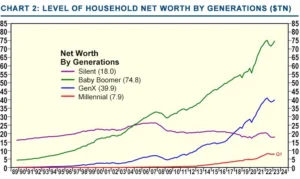
Social Strains. For much of the past three decades a disproportionate amount of income and wealth creation went to a smaller percentage of people, particularly those with capital in either the private or public markets. Most of today’s wealth resides within the Boomer generation (and this is concentrated in the wealthiest 10%). See Chart 2. Also, low income wages stagnated as many jobs moved offshore while minimum wages barely budged. This has strained social cohesion.


Government Policies/Debt. Government spending has skyrocketed. Given the flood of new money coming from the Infrastructure, Chips, and Clean Energy bills (on top of Entitlements and Defense increases), it is not likely to fall off. And of course, so much of it is borrowed (deficit spending) that the interest bill to the Federal government is soaring.

Geopolitical Realignment. Francis Fukuyama’s The End of History in 1989 suggested that after the fall of communism, Western liberal democracy had “won” and may be regarded as the final evolution of human government. For a time, this notion gained wide acceptance. Yet history did not end and there has been a rapidly growing divergence between liberal democracies and autocratic governments, particularly since Xi Jinping became president of China.

Technology. Advancements in technology over the past several decades have irrevocably changed the way we live and work. From the personal computer to the internet, email, smart phones, Zoom, and on and on. Now we are told that AI (artificial intelligence) will change our world even more dramatically than its precursors and at a faster pace.

Climate Change. Climate change is real although the causes extend far beyond fossil fuels. For example, just the increase in carbon dioxide from California’s 2020 wildfires was estimated in Environmental Pollution (10/22) to be twice the total of all California’s reductions over 15 years.

How might these disparate trends interact to mold our future?

Efficiency to Resilience. This is the force behind reshoring and increased defense budgets. Interest rates will be higher, inflation will likely be higher too as we turn from free markets and free trade toward industrial policies and managed trade. In addition, the impact of weather events – flooding, wind damage, extreme heat, droughts – will take ever greater resources just to fortify what is in place. This implies higher inflation and higher interest rates than we recently enjoyed.

Reductions in Inequality. Entitlement reform is essential if we are to pay for the increased demands on government. (Reduction in benefits to the wealthy and higher paid will be necessary.)

Wages will likely continue to rise across the bottom half of the income spectrum as a shrinking workforce increases labor’s bargaining power. Income taxes are likely to be even more progressive along with higher estate transfer costs.

New Global Powers. China may “hollow out” as it suffers from a rapidly aging workforce (a result of the one-child policy) along with the rise in capital flight and out migration by some of the wealthiest and brightest. The Middle East and Africa are likely to gain increasing power due to younger demographics and commodity wealth. India should benefit from its young, tech savvy workforce.

AI, the Wild Card. While many worry about a tragic Terminator type of outcome, there is real promise in areas like education, health care, and routine back-office services. If we are to have the long-awaited productivity boom, this will be the source.

Interest Rates, Credit, and Climate Change

The earth’s climate has changed many times over its history from bitter ice ages to much warmer periods. One statistical relationship holds true through all these periods, the higher the temperature, the less ice in the arctics and the higher the ocean level. So one variable, temperature, changes the configuration of all land masses.

The level of interest rates plays a similar role throughout the economy and the markets. Higher or lower interest rates change the entire financial landscape.

Almost all lending rates are tied to the Fed Funds Rate, the rate for overnight lending by the Federal Reserve (Fed). One example of direct ties are margin loans for our clients at Schwab which are often quoted at 2.0% plus the Fed Funds Rate. An example of indirect ties are 30-year fixed mortgage rates which have no direct ties to the Fed Funds Rate, but have sharply risen for borrowers.

Source: The Wall Street Journal

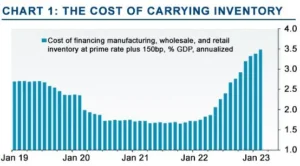
Carrying Costs. Higher interest rates raise the carrying cost of anything bought with credit… homes, automobiles, commercial buildings, capital equipment, inventories and so forth. See Chart 1.

As rates go up, fewer things are either affordable or make economic sense thus dampening economic growth. For example, a new business expansion that made good sense when the prime rate was 3.0% no longer works with its current 8.0% rate.

Less growth means less demand for goods and services which reduces inflation. This was the stated goal of the Fed as it raised the Fed Funds Rate over the past 12 months from effectively zero to now 4.75%-5.0%. It is working as inflation has steadily declined.

Housing is a good example. Home sales plummeted in 2022. As a result, the average home price came down (over 12 months) for the first time since the financial crisis. The ripple effects of less new housing are extensive – appliances, landscaping, furniture, and much more, all rise or fall with the housing industry.

Rollover Costs. After a decade of extremely low interest rates, most individuals and companies had financed their debts at very low interest cost, whether that be mortgages, bond issues, or virtually any other type of loan.

After the steep rise in interest rates over the past year, any debt that comes due, and needs to be rolled over, will jump to a much higher rate. This will reduce the cash available for other purchases, salaries, or capital investment.

Source: Haver Analytics, Rosenberg Research

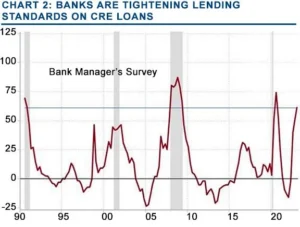
Commercial Real Estate (CRE) will have its highest dollar amount of rollovers in a generation this year. Already, major property owners such as PIMCO and Brookfield have walked away from properties they owned. Obviously, there will be more foreclosures and bankruptcies ahead. Banks will also be much more hesitant to rollover CRE loans. See Chart 2.

Hurdle Rates. Higher interest rates directly impact the risk/reward equation within investment choices. The higher the rate on “risk free” money market accounts, the more serious the competition (hurdle rate) they offer to other investments. Less risk taking by investors means less investment in economic activity.

Portfolio Declines. As the yields on newly issued bonds rise, the market value of previously issued bonds fall. It does not matter whether the bonds are super “safe” U.S. Treasury bonds, corporate bonds, mortgages, or municipals. This is what caused 2022 to be an especially bad year for virtually all bond investors.

Summary. The higher costs of carry and rollovers, as well as foreclosures, mostly occur when loans mature or new projects are deferred. This is why raising interest rates has a lagged impact of 6-12 months on economic activity. Even if the Fed is close to – or even at – the end of its rate rising, the impact of today’s rates will continue to slow the economy throughout 2023.

Fortunately, most of the economic impact is from the interest rate itself, not from the credit quality of the borrowers or the underlying investments. This means that as interest rates come down, much of the constrained economic activity can resume. The question then becomes, when does the Fed believe its inflation objective is achieved enough that it can begin that process.

What Is Behind Sustainable Progress?

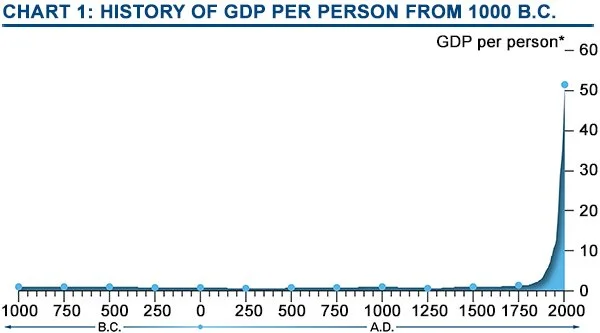
Between 1000 BC and 1750 AD the Bank of England estimates that the average person’s standard of living no more than doubled. That is little advancement over almost 3,000 years. Yet they estimate that from 1750 to today, the average has gone up over seven-fold. (Changes in standard of living are closely aligned with GDP per person.) See Chart 1.

The massive change in living standards that occurred over a handful of generations is nothing short of a miracle. Most Americans today live better and longer than the wealthiest kings of a few hundred years ago.

We owe this magnificent change in human history to the advancements in math, science, physics, and medicine that laid the groundwork for the steam engine, telegraph, railroad, electricity, automobile, telephone, vaccines, aircraft, automation, software, the internet, smart phone, cloud computing, and so much more.

Source: Bank of England

These are the more visible signposts that have been hallmarks of this age. However, there is much more to this story. Isaac Newton wrote in 1675, “If I have seen further (than others), it is by standing on the shoulders of giants.” In other words, each new bit of knowledge, each invention, is possible because of what has come before.

Much of the groundwork in basic sciences and math including geometry, astronomy, physics, and philosophy, was developed during Newton’s Age of Enlightenment. This was a period that saw the development of basic inventions necessary to our modern economy such as Gutenberg’s printing press.

Yet standards of living barely budged in this period. So, what was the “secret sauce” that unleashed the phenomenal economic growth of the past 250+ years in the Western world?

Two organizing concepts changed the world, democracy, and capitalism! Capitalism supplanted mercantilism as the basic economic model in England, Europe and particularly the United States, as spelled out in Adam Smith’s Wealth of Nations in 1776 … the same year of our independence. Mercantilism assumes a fixed economic pie (which meant you only grew more prosperous by taking someone else’s riches) while capitalism grows the economic pie and spreads it more broadly within the population.

Our new country’s inspired leaders, not burdened with the yokes of history, had the freedom to take from the best thinking of the giants who had come before. They delivered a true democracy – divided government, elected leaders, rule of law, an independent judiciary and Bill of Rights.

They encouraged free markets and the private ownership of land and inventions.

Alex de Tocqueville, the French sociologist and author, traveled widely throughout the United States in 1830 and 1831. The results of his travels and countless interviews led to his insightful masterpiece, Democracy in America (1835). Among its many revelations to Europeans (and Americans) was the individualism, freedom, and equality that Americans deeply believed in.

One insight that set America apart from virtually every other culture to this day was the trust Americans held in their fellow Americans. This supported the vast network of community, state, and federal associations as well as political, social, and economic structures thriving in America. Americans also exhibited tremendous depth of belief in their country and were willing to risk their lives in support of these beliefs. This was the basis of American Exceptionalism.

All of this went rushing through my mind as I watched Ukrainian President Volodymyr Zelensky address our Congress – in person – on the 21st of December. Here is a man leading a nation with such conviction, such belief, such courage, in the fight for the freedom of democracy and self-rule. The standing ovation given by Congress was not by party affiliation but by recognition of the continuing fight for principles.

Authoritarian rulers come and go, but little of lasting value comes from them. They coerce, bully, or bribe allegiance to themselves, not to principles. They typically drape themselves in the egalitarian promise of socialism or communism. In the end they often leave their country either backward or in ruin as seen in the rule by such strongmen as Stalin, Hitler, Mao, Castro, Maduro, and now Putin. Will Chairman Xi be next?

The turn to democracy and capitalism in the Western world underwrote the sustained progress of the past 250 years. But as shown by the unbelievable courage and will of the Ukrainian people, it should not be taken for granted.

“Money Has to Be Somewhere”

I find myself using this phrase often lately. Whether it is in stocks, bonds, investment real estate, money market accounts, gold, cryptos, or cash under the mattress… money must be somewhere. The concept of “money” is more of an accounting mechanism for balance sheets and income statements.

Every choice has its own characteristics which include:

  • Upside potential (moonshot or steady eddy)

  • Downside risk (erosion or wipeout)

  • Liquidity (ease of selling at the current estimate of value)

As most clients know, I did extensive research on asset class performance in the late 1980s. I developed our proprietary Historical Risk/Reward Charts as a way of comparing the risks and rewards of each investable asset class to each other.

With this analysis in hand, I developed “ideal” asset allocations to meet the wide variety of investor objectives which were first presented in 1990.

Our Historical Risk/Reward Charts are updated annually to present up-to-date guidelines as to the risk and reward of each asset class and asset allocation since 1972. Within each Historical Risk/Reward Chart:

Risk is defined as the percentage decline during bear markets (such as the one we are in today) as well as the length of time the portfolio was “underwater” (the total months of decline plus the total months to full recovery).

Reward is defined as the average annual return the portfolio delivered above the annualized riskless rate of 30-day Treasury bills for the same period.

Source: Tanglewood Total Wealth Management-Charts available on request.

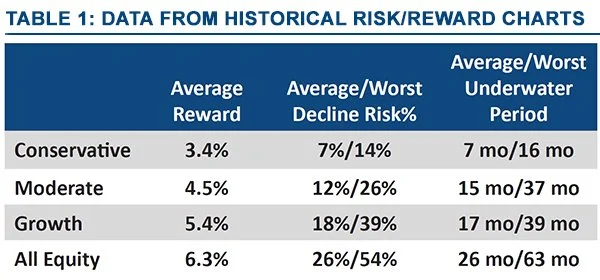
Table 1 shows the risks and rewards of Tanglewood’s four primary Investment Policies (IPs) as shown in their most recent Historical Risk/Reward charts (1972-2021). (A copy of these charts are provided in each client’s Tanglewood/Black Diamond Portal.)

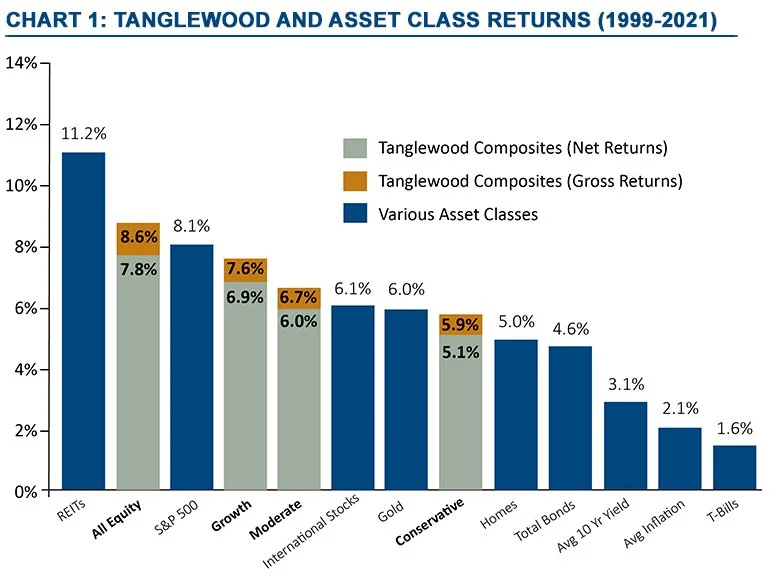
Chart 1 contains both asset class and Tanglewood IP composite performance for the period 1/1/99 through 12/31/21. This is not an arbitrary period, 1999 is the first year that Tanglewood’s performance was audited in accordance with GIPS standards. Both gross and net returns are shown for our four primary IPs — Conservative, Moderate, Growth and All Equity. Expanded performance information is provided on page 11.

Our performance calculations were verified over 17 years before dropping the audit in 2017 due to its increasing cost. However, we continued to follow the same procedures in calculating performances. We recently made the decision to resume our outside audits which will begin with where we previously stopped.

Source: Federal Reserve Economic Data (FRED), Tanglewood Total Wealth Management, Inc.

Money has to be somewhere and the asset classes in Chart 1 are the primary portfolio choices. This provides an excellent backdrop for our performance.

A very important confirmation of Tanglewood’s performance relative to that predicted by our Historical Risk/Reward Charts can be derived from the chart. The rewards of Tanglewood’s net returns over this period are almost identical to the rewards shown in Table 2. We delivered the expected returns over this period net of all fees and costs.

For example, Tanglewood’s Conservative indexed benchmark shows an annual reward of 3.4% since 1972 (Table 2). Since 1999, Tanglewood’s actual Conservative composite has provided a reward of 3.5% (Conservative’s 5.1% net average annual return is 3.5% greater than the average 1.6% return from treasury bills over this period.) Tanglewood’s Moderate, Growth and All Equity composites are equally close to those of their expected returns.